From idea to ETF portfolio in minutes. Build yours now →


Which Fixed-Income ETFs Benefit from Rising Interest Rates?
These fixed-income ETFs can potentially benefit from interest rate hikes through floating-rate exposure or higher short-term yields.

Keep up with what matters in ETFs
Get timely ETF insights, market trends, and top ideas straight to your inbox.
Your newsletter subscriptions with us are subject to ETF Central's Privacy Policy and Terms and Conditions.
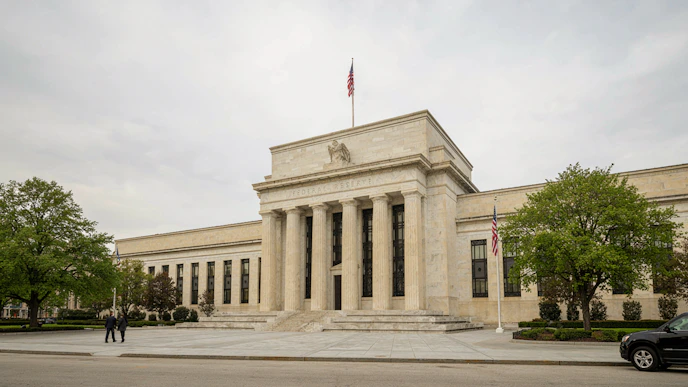
After keeping the federal funds rate at a target range of 3.50% to 3.75% for much of 2026, newly appointed Federal Reserve Chair Kevin Warsh and the rest of the Federal Open Market Committee unanimously agreed on September 16 to raise rates by 25 basis points to 3.75% to 4.00%. It was the Fed's first rate hike since 2023.
The Fed said economic activity continues to expand at a "solid pace," domestic spending remains resilient, capital investment is robust and inflation remains elevated. August's Consumer Price Index reinforced that concern, rising 3.4% year over year, with gasoline prices jumping 3.9% in August alone and accounting for more than one-third of the monthly CPI increase.
The backdrop includes higher energy costs associated with the ongoing Iran conflict, alongside an economy that has continued to absorb enormous capital expenditures related to AI. Warsh specifically pointed after the meeting to heavy capital spending by technology hyperscalers as one factor increasing demand for capital, while equity markets and the economy have remained comparatively resilient.
Investors who remember the inflation and rising-rate environment of 2022 already have some idea of what tighter monetary policy can do to a portfolio. Traditional fixed-rate bonds can be particularly vulnerable because newly issued debt begins offering higher yields, reducing the relative attractiveness of older bonds with lower coupons. The longer the bond's duration, the greater that sensitivity is.
Covered call strategies were one approach that gained considerably more attention during the previous inflationary period, in part because option premiums could provide another source of return when markets became more volatile. But today I'm staying entirely on the fixed-income side. That's particularly relevant because another hike remains a realistic possibility. Sixteen of 18 Fed policymakers currently project at least one additional increase before the end of 2026.
If rates do continue higher, not every bond ETF necessarily has to suffer. Two particular corners of the fixed-income market can actually become more attractive as short-term rates rise. Here's how they work and some of the ETFs investors can use to access them.
Like what you're reading?
Stay in the loop — get the latest ETF insights: trends, analysis, and expert picks.
Ultra-Short-Term Fixed Income
The simplest way to reduce the damage rising rates can inflict on bonds is to minimize duration. For this purpose, I'd go shorter than one year, focusing on securities that mature quickly enough for the portfolio to continually reinvest proceeds at prevailing rates.
That's the appeal of ultra-short-term fixed income in a hiking cycle. As the Fed raises rates, maturing securities can be replaced by newly issued ones carrying higher yields. Meanwhile, because duration is so low, the fund's net asset value generally experiences much less downward pressure from rising rates than an intermediate- or long-term bond ETF. From there, you can fine-tune the trade based on how much yield, credit risk and tax efficiency you want.
For maximum credit quality and potential state and local tax advantages, one option is the iShares 0-3 Month Treasury Bond ETF
As of September 16, SGOV had a 3.65% 30-day SEC yield after its 0.09% expense ratio. I'd expect that figure to adjust upward as the Fed's latest hike works its way through newly issued T-bills and the portfolio turns over. SGOV also pays monthly distributions, which can be more convenient for income investors than buying individual T-bills that are generally issued at a discount.
If you're willing to accept some additional credit risk and potentially less favorable tax treatment in exchange for more yield, there's the Vanguard Ultra-Short Bond ETF
That yield pickup comes from giving the managers considerably more freedom than SGOV. VUSB can venture beyond Treasuries into investment-grade corporate bonds, asset-backed securities and other short-term fixed-income instruments. Its average duration is correspondingly longer at roughly 0.9 years, but that's still low enough to keep its sensitivity to changing interest rates relatively modest.
Floating-Rate Bonds
Another way to position fixed income for rising rates is with floating-rate debt. Unlike a conventional bond with a fixed coupon, a floating-rate bond periodically resets its interest payment based on a short-term reference rate plus a predetermined spread. Common benchmarks include the Secured Overnight Financing Rate (SOFR) and short-term Treasury bill yields.
The basic appeal in a hiking cycle is straightforward: as the benchmark rises, the coupon can reset higher. As with ultra-short-term bonds, investors can then decide how far out on the credit-risk spectrum they're willing to venture in pursuit of additional yield.
At the conservative end is the WisdomTree Floating Rate Treasury Fund
Compared with simply owning T-bills, USFR’s appeal becomes more apparent if short-term rates continue climbing. A T-bill locks in its return until maturity, whereas the coupon on a Treasury floating-rate note resets weekly based on the latest 13-week T-bill auction rate, allowing income to adjust without waiting for the security itself to mature. Conversely, if rates fall, that reset mechanism works against you as the coupon adjusts downward.
If you're willing to accept more credit risk for additional yield, one option is the VanEck IG Floating Rate ETF
FLTR isn't limited to U.S. government debt. Roughly 21% of the portfolio is rated AA, 58% is rated A and another 20% is rated BBB, placing virtually the entire portfolio within investment grade. Financial issuers dominate at roughly 81% of assets, while the portfolio is geographically diversified, with U.S. securities representing only about 42%.
Companies issue floating-rate notes for many of the same reasons they issue conventional bonds: to raise capital for operations, acquisitions, refinancing and other corporate purposes. For investors, the attraction relative to Treasuries is the additional credit spread paid as compensation for taking corporate default risk. If benchmark rates rise, the coupon can reset higher while that credit spread provides additional income on top.
Finally, investors willing to move below investment grade can look at the State Street Blackstone Senior Loan ETF
Senior loans are floating-rate loans typically made to below-investment-grade companies. "Senior" refers to where the debt sits in the borrower's capital structure. These loans are generally secured by company assets and rank ahead of unsecured bonds and equity in the repayment waterfall if the borrower defaults. That doesn't eliminate credit risk, but the senior secured position can potentially improve recoveries compared with more junior claims.
There's another wrinkle here: SOFR floors. According to State Street, 31.86% of SLRN's loans currently have SOFR floors, with a weighted-average floor of 0.55%. A floor establishes a minimum benchmark rate used to calculate the loan's coupon. If SOFR drops below 0.55%, those loans would continue calculating interest using at least that 0.55% base rate, plus their contractual credit spread.
With three-month SOFR currently around 3.98%, however, those floors are far out of the money and provide no immediate benefit. The loans are already resetting off a benchmark substantially above their floors. In today's environment, the important feature is their floating-rate exposure: if SOFR moves higher, their coupons can generally move higher as well. The floors become more valuable if rates subsequently fall far enough to approach those minimum levels.
Please note that this article reflects the author’s personal views and does not represent the opinions of the publication or its affiliates. It is for informational purposes only and does not constitute investment advice. It is essential to seek guidance from a registered financial professional before making any investment decisions.
Latest ETF News
See all ETF newsMoneyShow Chart of the Day 9/4/26: Don't Just Watch Oil. Watch THESE.

Chart of the Day 8/14/26: The Great "Hot Money" Migration
MoneyShow Chart of the Day 7/29/26: Now, THAT's What I Call Market Rotation!
MoneyShow Chart of the Day 7/16/26: Good News/Bad News on Inflation (and the Fed)

 Advantages of ETFs over Mutual Funds1/6
Lower Costs
In this guide, we'll explore the advantages of ETFs over mutual funds, giving you valuable insights into why ETFs have gained significant popularity among investors like yourself.
Leveraged ETFs: Unlocking the Potential for Amplified Returns1/6
Understanding Leveraged ETFs
Explore leveraged ETFs: potential for amplified returns & risks. 5 ETFs to consider across equities, commodities & fixed income.
What is a Leveraged ETF?1/6
Introducing Leveraged and Inverse ETFs
In this guide, we'll dive into the world of leveraged ETFs, exploring their definition, mechanics, potential risks, and rewards.
Recent educational content
ETF Trends
ETF Industry KPIs September 14, 2026
This week’s KPI data overview highlights key metrics and trends shaping the ETF landscape.

ETF Trends
ETF Industry KPIs September 8, 2026
This week’s KPI data overview highlights key metrics and trends shaping the ETF landscape.
ETF Trends
ETF Industry KPIs August 31, 2026
This week’s KPI data overview highlights key metrics and trends shaping the ETF landscape.
ETF Trends
ETF Industry KPIs August 24, 2026
This week’s KPI data overview highlights key metrics and trends shaping the ETF landscape.
Browse all educational columns


Expert-Built ETF Portfolios, All in One Place
Don’t start from scratch. Discover ready-made ETF portfolios built by professionals to match different goals, timelines, and market views. Use them as inspiration or as a starting point for your own allocation.