ETF model portfolios designed for real investor needs. Discover →

What is a Boomer Candy ETF?
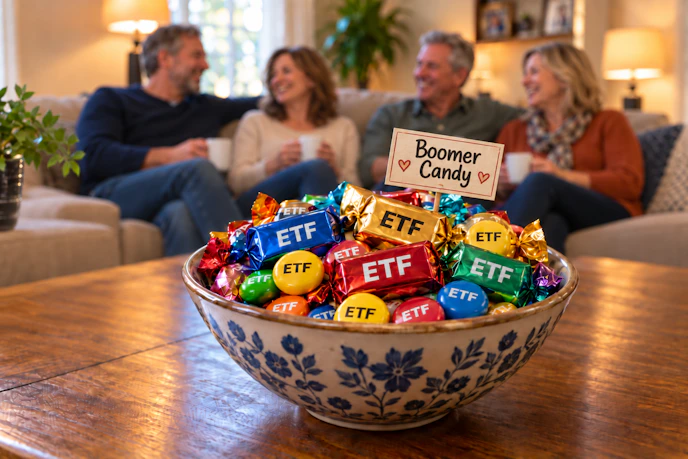
“Boomer candy” ETFs sell a simple promise: more income, less volatility. These two funds show what that looks like in practice.

Keep up with what matters in ETFs
Get timely ETF insights, market trends, and top ideas straight to your inbox.
Your newsletter subscriptions with us are subject to ETF Central's Privacy Policy and Terms and Conditions.
The unusual combination of high inflation and rapidly rising interest rates during the 2022 bear market soured plenty of older, more risk-averse investors on the traditional 60/40 portfolio. With both major asset classes moving in the same direction (downwards), the bond allocation provided considerably less protection against equity losses than investors had come to expect.
Around that time, I started noticing financial media outlets including The Wall Street Journal, Bloomberg, and the Financial Times increasingly referring to a new generation of investment products as "boomer candy."
There isn't really an agreed-upon definition. I've seen the term applied to everything from covered call funds and buffer ETFs to low-volatility strategies.
So, allow me to propose one of my own: in my view, a boomer candy ETF is one that uses derivatives, particularly options, to pursue two objectives simultaneously: higher income and lower volatility.
That distinction excludes conventional covered call and buffer ETFs on their own. A covered call ETF may substantially increase income, but it still retains considerable downside exposure to its underlying stocks.
A buffer ETF can reduce losses over a defined outcome period, but it isn't necessarily designed to generate substantial income.
For my definition, an ETF needs to address both objectives.
It's easy to understand why that combination might appeal to retirees. Lower volatility can reduce the severity of portfolio drawdowns and, importantly, the sequence-of-returns risk created by withdrawing money during a bear market.
Higher distributions can simultaneously provide regular cash flow without requiring investors to sell as shares to fund expenses.
Before ETFs packaged these strategies, investors generally had fewer choices. They could increase allocations to cash and bonds, purchase an annuity, or, with the assistance of a sufficiently sophisticated advisor, use structured notes and customized options strategies.
Each came with its own limitations involving liquidity, complexity, cost, or flexibility.
The ETF wrapper makes these strategies considerably easier to access. Investors can receive periodic distributions, potentially benefit from more favorable tax treatment depending on how the options are structured, and retain intraday liquidity rather than locking capital into an insurance contract or structured product.
Here’s a look at two ETFs that fit my definition of boomer candy.
Global ETF Survey 2026 is Live!
With 1,790 new products launched by July 2026, choosing is harder than ever. Our Global ETF Survey 2026, built on 620 professional investors and allocators, shows how active, fixed income, options-based and thematic ETFs are reshaping fund selection.
NEOS S&P 500 Hedged Equity Income ETF (SPYH)
The NEOS S&P 500 High Income ETF (SPYI) has become a major success in the covered call category, swelling to approximately $11.59 billion in assets under management. Much of its appeal comes from a 12.04% distribution rate that has historically been composed largely of return of capital (ROC).
Its far smaller sibling, the NEOS S&P 500 Hedged Equity Income ETF (SPYH), manages only about $31 million and currently offers a lower 7.93% distribution rate. There is a reason investors receive less income: some of the option premium that could be distributed is being spent on downside protection.
The strategy starts with S&P 500 equity exposure and a covered call overlay. From there, NEOS adds a put spread collar designed to reduce downside risk.
The long put is the primary hedge. Buying a put gives the portfolio the right to sell at a predetermined strike price, meaning it begins offsetting losses once the S&P 500 falls sufficiently far. The problem is that puts cost money, and continuously purchasing portfolio insurance can create significant negative carry.
To help finance that protection, the strategy also sells a lower strike put. That premium reduces the cost of purchasing the higher-strike protective put, but it also limits how much downside protection the put spread ultimately provides. Once the market falls through the lower strike, losses can begin again.
Combine that put spread with the premium received from selling covered calls and you get a net credit put spread collar. "Net credit" means the premiums collected from the short options are intended to exceed the premium paid for the protective long put. Instead of continuously paying out of pocket for portfolio insurance, the overall options package can still generate net premium.
That's what makes the strategy fit my definition of boomer candy.
Part of the option premium is available to support distributions, while another portion effectively pays for a buffer against market volatility. Investors shouldn't mistake that for complete downside protection though.
The hedge only covers a defined range of losses.
The protective put begins providing protection after its strike is breached, but because a lower strike put has also been sold, that protection eventually runs out during a sufficiently severe market decline. Meanwhile, the covered calls continue to limit some upside participation during strong rallies.
Tax efficiency is another attraction.
Like SPYI, the fund uses S&P 500 Index (SPX) options, which generally qualify as Section 1256 contracts.
Gains and losses on these contracts receive 60/40 federal tax treatment, meaning 60% are treated as long-term and 40% as short-term regardless of how long the options were actually held.
The distribution itself has also been relatively tax-efficient so far.
According to the fund's latest Section 19(a) notice, approximately 90% of the most recent distribution was estimated to be return of capital, which generally isn't immediately taxable when received.
Instead, it reduces the investor's cost basis, potentially deferring taxes until the ETF shares are eventually sold. As always, Section 19(a) classifications are estimates rather than final tax determinations.
Kensington Hedged Premium Income ETF (KHPI)
Competing directly against SPYH is the Kensington Hedged Premium Income ETF (KHPI), which has attracted considerably more investor interest so far, accumulating $428 million in assets. KHPI currently advertises a higher 9% distribution rate, although investors pay considerably more for the strategy. Its 0.98% expense ratio compares with 0.68% for SPYH.
The portfolio begins with exposure to the S&P 500, obtained through a combination of low-cost underlying ETFs and futures contracts. Kensington then adds two options components designed to simultaneously reduce volatility and generate income.
The first consists of put spreads on a quarterly basis. As discussed earlier, a put spread generally involves purchasing a put to establish downside protection while selling another put at a lower strike to offset some of the cost. The protection therefore covers a defined range of market losses rather than insuring the portfolio all the way to zero, which is much more expensive.
To help generate income and offset the cost of those hedges, KHPI also sells call spreads. The fund sells a call option while simultaneously purchasing another at a higher strike. Because the lower-strike call being sold is more valuable than the higher-strike call being purchased, the trade generates a net credit.
If the S&P 500 rises above the short call's strike, that position begins working against the portfolio's gains. However, once the index rises above the higher strike of the purchased call, the long call begins offsetting further losses on the short call. Depending on how those spreads are positioned, that can potentially preserve more upside than a conventional covered call strategy.
So far, the risk statistics suggest the hedging component has done its job. According to Kensington, through June 30, 2026, KHPI exhibited annualized standard deviation of 9.23%, compared with 13.39% for the S&P 500. Its maximum drawdown was also shallower at 4.93%, versus 7.50% for the benchmark.
The fund's capture ratios provide another useful perspective. KHPI recorded an upside capture ratio of 62.74% and a downside capture ratio of 63.03%. In other words, it historically participated in roughly similar proportions of the market's advances and declines over the period measured.
Please note that this article reflects the author’s personal views and does not represent the opinions of the publication or its affiliates. It is for informational purposes only and does not constitute investment advice. It is essential to seek guidance from a registered financial professional before making any investment decisions.
Topics
See all
Segments
See all
Mentioned ETFs
Further reading
Latest ETF News
See all ETF newsBeyond Big Tech: The Increasing Specialization of AI ETFs
There's an ETF for That? Humanoid Robotics and Physical AI
How Some ETF Issuers Use Their Own Funds for Cash Management
These Public-Private ETFs Invest in Polymarket and Anduril
There's an ETF for That? Frontier Markets
 Advantages of ETFs over Mutual Funds1/6
Lower Costs
In this guide, we'll explore the advantages of ETFs over mutual funds, giving you valuable insights into why ETFs have gained significant popularity among investors like yourself.
Leveraged ETFs: Unlocking the Potential for Amplified Returns1/6
Understanding Leveraged ETFs
Explore leveraged ETFs: potential for amplified returns & risks. 5 ETFs to consider across equities, commodities & fixed income.
What is a Leveraged ETF?1/6
Introducing Leveraged and Inverse ETFs
In this guide, we'll dive into the world of leveraged ETFs, exploring their definition, mechanics, potential risks, and rewards.
Recent educational content
First Look ETF
First Look ETF: Income, International, and Cash Flow ETFs
In this season 6 episode of First Look ETF, Stephanie Stanton @etfguide examines the latest ETF marketplace trends with NYSE and guests.

ETF Trends
ETF Industry KPIs October 5, 2026
This week’s KPI data overview highlights key metrics and trends shaping the ETF landscape.

ETF Trends
ETF Industry KPIs September 28, 2026
This week’s KPI data overview highlights key metrics and trends shaping the ETF landscape.
ETF Trends
ETF Industry KPIs September 22, 2026
This week’s KPI data overview highlights key metrics and trends shaping the ETF landscape.